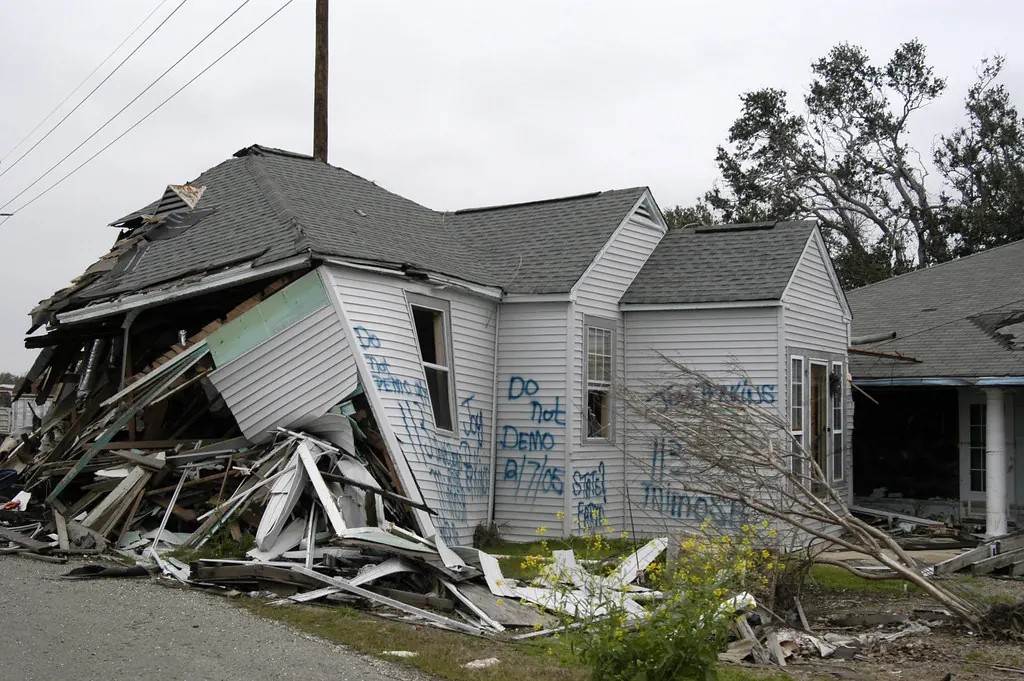
Claim risks in New Bedford
- Hurricanes
- Nor’easters
- Wind-driven rain
- Fire
- Burst pipes
A harbor city shaped by storms
New Bedford sits on Buzzards Bay in Bristol County, and its harbor has taken some of the worst storms in New England history. The Great New England Hurricane of 1938 and Hurricane Carol in 1954 both brought severe flooding to the waterfront. After those storms, the federal government built the New Bedford hurricane barrier, a large stone and earth dike with gates across the harbor entrance, finished in the 1960s.
The barrier protects much of the inner harbor from storm surge, but it does not stop wind. Hurricanes and nor’easters still bring damaging wind and driving rain to the city, and areas outside the barrier, including parts of Clarks Point and the South End shoreline, are more exposed.
Neighborhoods and housing
The North End and South End are dense with triple-deckers and multi-family homes, many built for mill and fishing workers. The historic downtown has whaling-era homes and brick commercial buildings. County Street has large older homes, and the West End mixes two-families and single homes. Former mill buildings around the city have been converted to housing and business space.
Older triple-deckers bring porches, low-slope roofs and layered siding. Whaling-era homes may have plaster, original windows and trim that cost more to repair than estimates often allow.
Common New Bedford claim issues
- Wind-driven rain damage treated as wear or maintenance.
- Triple-decker losses that touch several units and policies.
- Siding and roof repairs on older homes priced without matching.
- Percentage wind or hurricane deductibles applied to coastal homes.
- Fire and smoke damage in neighboring buildings.
Triple-decker claims
New Bedford has a large stock of triple-deckers, and they bring special claim questions about stacked porches, shared roofs and multiple owners or tenants. Our guide on triple-decker insurance claims covers the most common sticking points. If the carrier’s estimate falls short, appraisal under the policy may provide an independent amount of loss.
Massachusetts property policies are built around the state’s standard fire policy, which includes a process often called reference, where disinterested referees set the amount of loss. Many homeowner forms call it appraisal. It does not decide coverage or claim-handling questions; for those, consult a Massachusetts attorney. Our role is narrower: pricing the repair accurately and presenting it clearly.
Services for New Bedford property owners
Every Massachusetts Insurance Appraiser service is available in New Bedford and the surrounding towns, including:
- Appraisal Representation
- Home Insurance Claims
- Condo, HOA & Commercial
- Roof & Hail Damage
- Wind & Tornado Damage
- Hurricane & Nor’easter Claims
New Bedford questions
Does the hurricane barrier lower my insurance risk?
The barrier reduces storm-surge flooding for much of the inner harbor. It does not prevent wind damage, and homes outside the barrier can still face surge. Your insurer sets rates and deductibles by its own rules.
Is a New Bedford triple-decker covered differently from a single-family home?
It can be. Owner-occupied buildings are often on homeowner forms; fully rented buildings may be on dwelling or commercial policies. The wording affects coverage and appraisal.
Can you help with an older whaling-era home?
Yes. We review claims on older homes where plaster, trim and windows need careful pricing.